
Compliance letter for equipment purchased on government funded awards.
Resources
If you see this error, when trying to look at your Account Certifications:
You have limited or no access to the Account Certification ledger balances. Please contact your Administrator.
No – you cannot add attachments or notes to the Account Certification after it’s been submitted.
Match Exceptions FAQ (QRG)
This FAQ contains frequently asked questions pertaining to Match Exceptions. Use the table of contents below to control + click to go directly to that question and answer. For step-by-step guidance on how to find and address a match exception, review the Match Exception Investigation and Correction QRG.
Stakeholders can use this Cheat Sheet to determine which course(s) will best address their Workday Financials questions. These courses are available as self-paced training and can be searched by title in Workday Learning.
Self-Paced Training Cheat Sheet.pdf138.07 KB
The Decision Tree maps out corrections paths for certain tasks. See file at the bottom of the page for a graphic decision tree.
Workday tasks used to correct the FDM worktags on posted transactions
Internal Service Delivery:
Correction Decision Tree.pdf134.59 KB
How do I process a refund for revenue?
If you have deposited revenue, you may come across times that you need to refund the customer. The process for refunding the money is different depending on how the revenue came into the university.
How will Named Professorships appear in Workday?
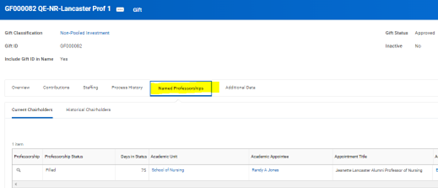
The Primary Gift will have a new attribute tab labeled “Named Professorship”
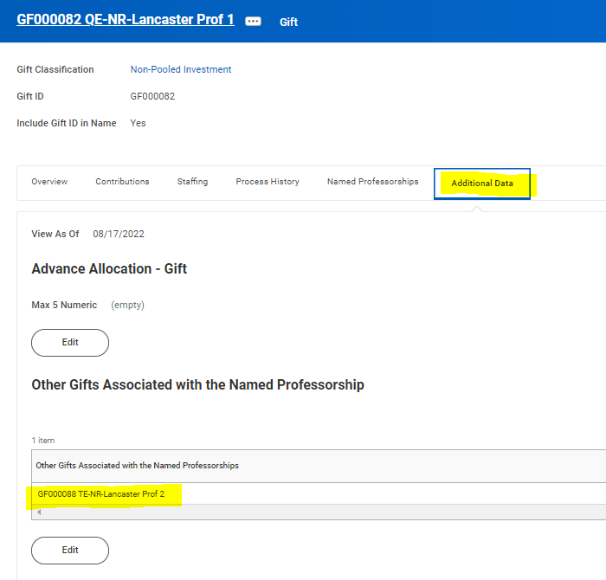
Any additional Gifts associated will be identified in the “Addition Data” tab on the Primary Gift
All Named Professorships will be flipped from being linked to a Basic Gift to the Workday Financials Gift Worktag. To preserve specific information for HCM during that flip, they have asked that we add a naming convention to the Named Professorships.
Units will see the Primary Gift linked to the Named Professorship. When Gifts are linked to Named Professorships, the Gift Worktag gets a new “tab” on the Worktag landing page which will allow users to navigate back and forth between Gift and Named Professorship. This does not impact any accounting functionality; it's just to aid in navigation.
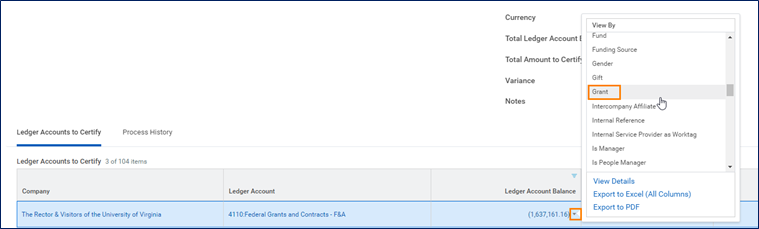
The 4100: Federal Grants and Contract ledger account, is where grant revenue is posted. This will look different depending on Contract Line Type. If the Grant is a Cost Reimbursable grant, you will see the amount in the 4100 ledger account line match the total expenditures including the F&A expenditures because this is the amount that will be reimbursed by the sponsor when invoiced by OSP. You may see this as 0.00 in the Total Ledger Account Balance.
What am I responsible for when reconciling for grants?
Your focus when working on a Grant Account Certification should be on certifying that the expenditures in the expenditure ledger accounts are appropriate or marking a variance if they are not.
If you are a reconciling a Gift, Grant, or Designated, and you see Funding Source Reclassification transactions:
The United States has tax treaties with several foreign countries. Under these treaties, residents (not necessarily citizens) of foreign countries are taxed at a reduced rate, or exempt specific income amounts of U.S.-sourced income and/or scholarship/fellowship payments from taxation. Please see the list below to see if your country has a tax treaty.
University of Virginia's Standard Service Terms and Conditions for when UVA is the service provider.
UVA_STC.pdf72.19 KB
Guidelines for Developing Some Common Types of Academic Program Agreements
Virginia State and Local Government Conflict of Interest Act
It is our policy to review and update uncashed checks annually. State law requires us to report and remit the funds to the state if the check is uncashed for a specific period of time. To prevent us from reporting and remitting your check to the state unclaimed property office, please respond to us no later than September 30, 2026.
What is a Form 1042-S, and when should I receive it?
A 1042-S is a year-end federal tax document given to a non-resident alien who received wages exempted from federal and state tax withholding by a tax treaty received a non-qualified taxable scholarship